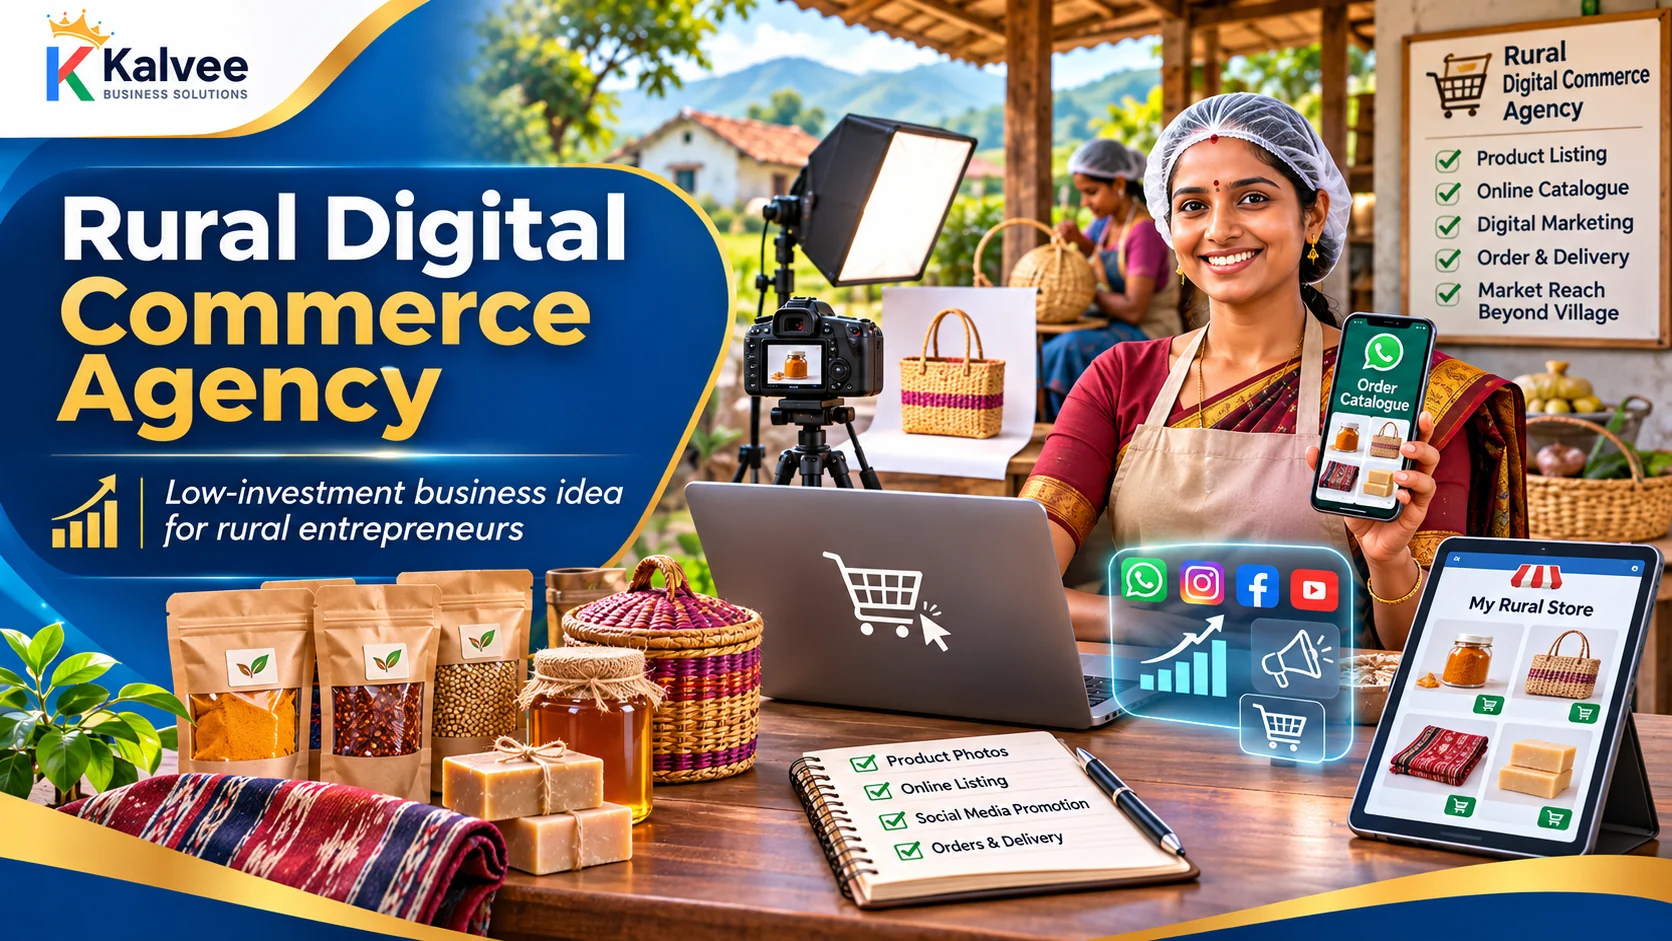
Create a laptop-first local agency offering simple business listings, product photography, WhatsApp Business catalogues, social-media posting and permitted online seller onboarding. Start with clear client deliverables instead of promising viral growth.
Rural Digital Commerce & Catalogue Service Agency
Help village shops, SHGs and artisans photograph products, build catalogues and manage online customer enquiries.
1. Business model and operating process
Audit client products → sign scope/consent → shoot and edit photos → collect accurate prices/stock → create catalogue/listings → train owner → report enquiries and hand over accounts.
Pilot three fixed-price service packages; use a client-owned business account and documented permissions.
2. Initial investment and equipment budget
Indicative project budget: ₹22,000. A smaller entry pilot may start around ₹5,000–₹25,000 where existing premises and equipment are available. Obtain at least three written vendor quotations, including transport, installation, GST and warranty before applying for finance.
| Investment or initial provision | Illustrative amount |
|---|---|
| Design and catalogue software provision | ₹5,000 |
| Simple website/domain and templates | ₹3,000 |
| Phone tripod, light and photo backdrop | ₹3,000 |
| Data and communication setup | ₹2,000 |
| Village travel and outreach | ₹3,000 |
| Working-capital reserve | ₹6,000 |
| Total | ₹22,000 |
Total planned investment: ₹22,000. The estimate includes a limited buffer but does not include land purchase or major permanent construction.
3. Production, manpower and safety
Existing laptop or smartphone, camera/light kit, secure data storage, mobile connectivity, design tools, standard contracts and lightweight website setup.
Audit client products → sign scope/consent → shoot and edit photos → collect accurate prices/stock → create catalogue/listings → train owner → report enquiries and hand over accounts.
Start with owner-led operations and add labour only when paid orders justify it. Confirm access to suitable space, water or electricity where needed, and maintain purchase bills, inventory, safety and quality records.
4. Illustrative monthly sales, costs and remainder
Monthly sales assumption: 8 paying clients per month at an average ₹2,500 service fee each. This produces ₹20,000 in hypothetical monthly sales. The monthly cost model explicitly includes an allowance for the owner’s labour.
| Monthly operating expense | Illustrative amount |
|---|---|
| Software, hosting and connectivity | ₹3,000 |
| Village visits and photography travel | ₹2,000 |
| Freelance editing / admin support | ₹3,000 |
| Owner labour allowance | ₹9,000 |
| Miscellaneous and customer support | ₹1,500 |
| Total | ₹18,500 |
−
=
7.5% of illustrative sales after the listed expenses. Actual income may be lower or negative.
₹18,000 only if the same monthly operating model runs for 12 months. Seasonality, initial ramp-up, tax and loan principal repayments can materially change cash flow.
Do not use this as a bank-certified DPR. Build a fresh 12-month cash-flow forecast from local quotations, order evidence, actual production cycles, a prospective loan repayment schedule and taxes applicable to the applicant.
5. Customers, sales channels and validation
Customer segments: SHGs, rural artisans, farm-product brands, kirana shops, tailoring units, service professionals and local manufacturers.
Revenue assumes paid customers and excludes any promised ecommerce sales conversion; service fees should be collected against agreed milestones.
- Interview at least 20 prospective customers and record expected quantity and price.
- Request trial purchase orders or paid pilot commitments where practical.
- Keep receipts and records for each order, cancellation and repeat sale.
- Track selling price after discounts, packaging, commissions, tax and delivery.
6. Registrations, quality standards and compliance
Consider Udyam registration if eligible, local business registrations and GST as relevant to turnover/service type. Comply with data protection, platform policies, intellectual-property rights, advertising claims and client consent; never claim official ONDC affiliation without authorisation.
7. Government programmes and bank finance
MSME TEAM provides certain support for eligible MSE participants in digital commerce/ONDC via approved programme channels; it is not a blanket cash subsidy to an independent catalogue agency. MUDRA or PMEGP may be explored for an eligible new services business, subject to lender/programme conditions.
For a loan request, prepare applicant KYC, PAN, premise ownership/lease documents, project report, three vendor quotations, market demand evidence, projected cash flows and registration or sector certificates where applicable. Contact the bank or implementing agency about activity-specific eligibility and current applications.
Find state or UT scheme references
Choose a State / Union Territory to explore programmes that may be relevant to this project. State startup policies are not automatically subsidies for ordinary rural businesses.
Find government schemes for your business
Choose your state or Union Territory and business category. Review possible funding, who may qualify, required documents and the official route to apply.
Central government schemes available across India
Displayed programmes are leads to investigate, not confirmed eligibility or an offer of funding. An application may be closed or subject to a bank/department selection process.
Prime Minister Employment Generation Programme (PMEGP)
Subsidy: generally 15%–35% of eligible project cost; project ceiling ₹50 lakh manufacturing / ₹20 lakh service
Eligible applicants aged 18+ proposing a qualifying new micro-enterprise. Location, applicant category, project type and scheme exclusions affect subsidy.
Photograph, Aadhaar, PAN, project report, education certificate where applicable, category/rural area certificates where relevant, bank particulars.
Read KVIC eligibility and negative list → prepare DPR and quotations → apply on the PMEGP portal → agency screening, bank appraisal and training where required.
Official rules govern approval. Confirm availability and required documents with the implementing agency.
View official details / application ↗Pradhan Mantri MUDRA Yojana (PMMY)
Loans: Shishu up to ₹50,000; Kishore to ₹5 lakh; Tarun to ₹10 lakh; eligible repeat Tarun Plus borrowers to ₹20 lakh
Qualifying non-corporate micro enterprises and applicable allied activities. Tarun Plus requires successful repayment of an earlier Tarun loan. This is credit, not a subsidy.
KYC/PAN, address proof, business plan, relevant quotations, business/bank statements, income information as requested by lender.
Compare participating lenders → prepare business plan and KYC → apply through lender or JanSamarth (if offered) → lender credit assessment.
Official rules govern approval. Confirm availability and required documents with the implementing agency.
View official details / application ↗PM Formalisation of Micro Food Processing Enterprises (PMFME)
Credit-linked capital subsidy: 35% of eligible project cost, up to ₹10 lakh per qualifying individual unit
Qualifying new or existing micro food-processing enterprises; not automatically available for a restaurant, tiffin delivery or café. Minimum applicant contribution generally 10%.
KYC, registration details, DPR, machinery quotations, site/land details, bank information, product and financial details specified by PMFME.
Verify processing activity and district ODOP rules → contact District Resource Person → prepare DPR → apply on the PMFME MIS portal → bank and department assessment.
Official rules govern approval. Confirm availability and required documents with the implementing agency.
View official details / application ↗Startup India Seed Fund Scheme (SISFS)
Up to ₹20 lakh grant for proof of concept/prototype; up to ₹50 lakh via debt/convertible instruments for commercialization
DPIIT-recognised innovative startup, normally incorporated not more than two years before application, subject to full scheme conditions and available incubator funding.
DPIIT recognition, incorporation/PAN, pitch deck, innovation/product details, prototype or validation evidence, financial forecast, founder KYC and incubator-specific documents.
Obtain DPIIT recognition → check open incubator calls → apply through official Seed Fund portal → pitch/evaluation → milestones and fund agreement if selected.
Official rules govern approval. Confirm availability and required documents with the implementing agency.
View official details / application ↗8. First 30 days — practical launch checklist
- Days 1–7: Interview 20 local businesses and collect sample catalogue requirements
- Days 8–14: Create three service packages with terms, handover clauses and transparent monthly charges
- Days 15–21: Build two paid pilot catalogues with written photo and listing permissions
- Days 22–30: Measure qualified enquiries, repeat client retention and delivery time before hiring
9. Business risks and safeguards
High client churn, poor product photography, incorrect prices, privacy problems, weak connectivity and platform account disputes. Always keep seller credentials with the client and obtain written approval before publishing or running ads.
10. Official sources and useful institutions
Need help preparing a customised project report?
Kalvee Business Solutions can help organise your business documentation, registrations and planning assumptions. Only your lender and scheme authority can approve any credit, subsidy or incentive.
Editorial disclaimer — 17 November 2026: All costs and income examples here are illustrative, independently constructed estimates. No business has been inspected for these figures; official scheme eligibility and support amounts may change. Consult the appropriate authority and licensed professionals before investing, hiring or borrowing. Visit kalveebsolutions.com for more resources.
Starting this business?
We handle the registrations new businesses need across India: Udyam, GST, shop licence, FSSAI, and PF and ESIC once you hire. Get a new idea every day on our WhatsApp channel.
Indicative information for planning, not financial or legal advice. Budgets, licences and scheme rules vary by state, city and scale. Check with the issuing authority before you invest.